Personal Finance Tips for 2026: 12 Smart Moves
The most useful personal finance tips are not complicated; they are simply applied consistently. In 2026, with prices still shifting and interest rates rarely sitting still, small disciplined habits beat dramatic one-off gestures every time. This guide gathers twelve practical moves you can start this month, each chosen because it works for real budgets rather than theoretical ones.
You do not need a finance degree or a six-figure salary to get ahead. You need a clear plan, a little automation and the patience to let compounding do its quiet work. Let us turn good intentions into a system that runs itself.
Why Do Personal Finance Tips Matter in 2026?
Money stress is rarely about the numbers alone; it is about the lack of a plan. Solid personal finance tips give you a framework so decisions become routine instead of stressful. When your saving and bill-paying happen automatically, you free up mental energy for the choices that actually move the needle.
Recent data from the Federal Reserve’s report on the economic well-being of U.S. households shows many adults still could not cover a modest emergency expense with cash. A simple, repeatable system is what closes that gap.
What Are the Foundation Habits?
Before chasing investments, lock down the basics. These foundation habits create the stability that every other move depends on.
- Write a zero-based budget so every dollar has a job.
- Automate an emergency fund targeting three to six months of expenses.
- Pay yourself first by moving savings on payday, before spending.
- Track your net worth monthly to see progress at a glance.
None of these require extra income. They simply reorder when and how you move the money you already have, which is where most lasting progress comes from.
Which Money Moves Build Wealth Fastest?
Once the foundation holds, these growth-focused moves accelerate your results. The table shows the effort each takes against the payoff you can expect.
| Move | Effort | Payoff |
|---|---|---|
| Kill high-interest debt | Medium | High, guaranteed return |
| Capture employer match | Low | High, instant free money |
| Invest monthly in index funds | Low | High, over the long term |
| Cut recurring subscriptions | Low | Medium, immediate |
| Raise your income skill | High | Very high, compounding |
Notice how many high-payoff moves demand low effort. Capturing an employer retirement match, for instance, is close to free money, yet plenty of people leave it on the table year after year.
The Remaining Smart Moves
To complete the dozen, add these habits that protect and compound what you build.
- Review subscriptions quarterly and cancel the ones you forgot.
- Negotiate recurring bills such as insurance and internet once a year.
- Keep a 24-hour rule for any non-essential purchase over a set amount.
- Check your credit report for errors that quietly raise borrowing costs.
- Set one measurable money goal per quarter and track it.
- Revisit your plan after life changes like a raise, move or new family member.
- Use the right tools to automate and monitor everything above.
- Invest in learning so your highest-value asset, your earning power, keeps growing.
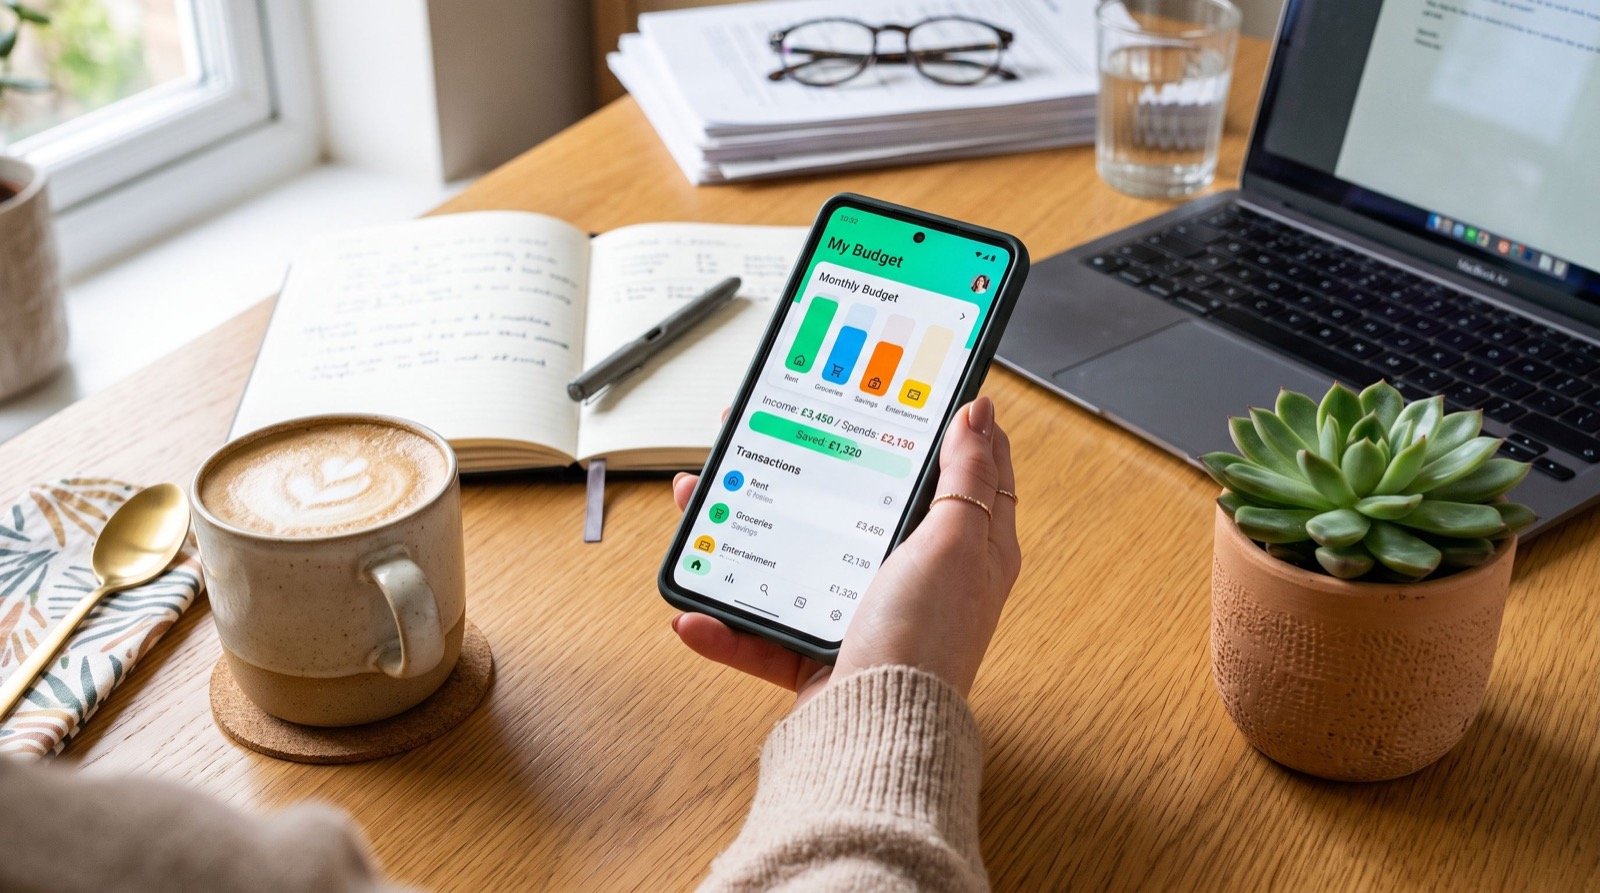
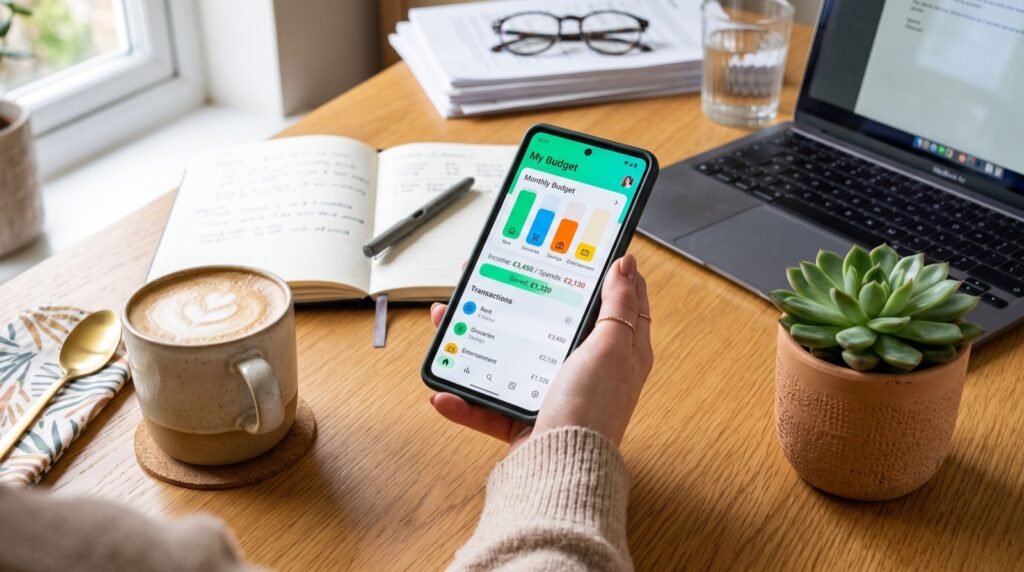
Tools matter because willpower fades. The right money apps can automate savings, flag overspending and keep your goals visible, turning these tips into defaults you no longer think about.
Turning Tips Into a System
A list only helps if it becomes routine. Pick two moves this week, automate them, then add another pair next month. Within a quarter you will have a self-running system rather than a pile of good intentions.
Schedule a short monthly money check-in with yourself. Fifteen minutes to review spending, savings and goals keeps you honest and lets you course-correct early. For more in-depth personal finance tips and tool comparisons, lean on resources that test advice against real budgets.
If a major expense such as a household move is on your horizon, planning the budget early with dependable specialists helps you avoid the last-minute costs that wreck a savings plan.
How Do You Stay Motivated Over the Long Run?
Motivation fades; systems endure. The reason most financial plans fail is not bad advice but lost momentum around week three. Beat that by making progress visible and celebrating small wins along the way.
Keep a simple tracker, whether a spreadsheet or an app dashboard, that shows your savings line climbing. Watching the number grow is genuinely motivating and turns an abstract goal into something you can feel. Pair each milestone with a modest, planned reward so discipline never feels like pure deprivation.
Accountability helps too. Share a goal with a trusted friend or partner, or join a community working toward similar targets. Knowing someone will ask how it is going nudges you to keep the habit alive on the days motivation runs thin.
Common Money Mistakes to Avoid in 2026
Knowing what not to do is as valuable as any positive habit. These errors quietly undo progress for even disciplined savers, so guard against them deliberately.
- Lifestyle creep: letting spending rise in lockstep with every raise.
- Ignoring small recurring costs: forgotten subscriptions drain hundreds a year.
- Carrying a credit-card balance: high interest erases investment gains.
- No written plan: vague goals rarely survive contact with real temptation.
- Timing the market: steady investing beats guessing the perfect moment.
Each mistake is easy to avoid once you can name it. Review this short list whenever you feel your budget slipping, and you will usually spot the culprit within a minute or two.
Frequently Asked Questions
What is the single most effective personal finance tip?
Pay yourself first. Automatically moving a set amount into savings or investments on payday, before you can spend it, quietly builds wealth faster than any budgeting trick you apply later.
How much should I keep in an emergency fund?
Aim for three to six months of essential expenses. Start with a smaller starter buffer if that feels daunting, then build it up through automatic monthly transfers.
Should I pay off debt or invest first?
Clear high-interest debt first, since its guaranteed cost usually outweighs expected investment returns. Still capture any employer retirement match, because that is an immediate return you should not skip.
Do I need apps to manage my money well?
No, but good apps make consistency far easier by automating transfers and tracking. They remove the willpower problem that derails most well-meaning plans.
Conclusion
These personal finance tips work because they are simple, repeatable and built around automation rather than willpower. Lock in the foundation habits, layer in the high-payoff moves, and let the right tools keep everything running in the background through 2026 and beyond. Choose two moves today, automate them before the week ends, and let steady, boring consistency quietly build your wealth.